Polypropylene Buyers' Guide: How to Source PP When Middle East Supply Is Blocked
Introduction
For decades, polypropylene (PP) buyers across Europe, Asia, Africa, and the Americas relied heavily on Middle Eastern producers for stable, competitively priced supply. Major suppliers such as SABIC, BOROUGE, and EQUATE became integral parts of global polymer supply chains.
However, the disruptions of 2026 have fundamentally altered that landscape.
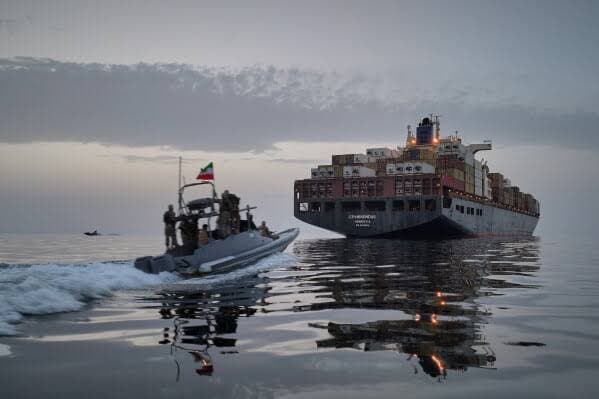
The Hormuz conflict and resulting shipping constraints have significantly reduced the availability of Middle Eastern polypropylene exports, forcing procurement teams to rapidly reassess sourcing strategies. While demand from packaging, automotive, consumer goods, and industrial manufacturing sectors remains strong, the traditional supply map has been redrawn.
For buyers, the challenge is no longer simply finding polypropylene—it is identifying reliable alternative suppliers, qualifying new grades, and building supply chain resilience for the future.
Why Polypropylene Supply Chains Have Changed
The global polypropylene market has historically depended on Middle Eastern production due to the region's abundant feedstocks and export-oriented manufacturing capacity.
When supply disruptions affected major exporters in 2026, buyers faced:
Reduced material availability
Longer lead times
Higher freight costs
Increased price volatility
Greater competition for available volumes
Unlike temporary disruptions seen in previous market cycles, many industry participants now believe the shift toward diversified sourcing will continue even after regional logistics normalize.
As a result, procurement teams are actively qualifying suppliers from North America, China, India, and Europe.
Alternative Supply Sources by Region
North America: US Shale-Based Producers
For buyers located in North America, domestic and regional producers offer the most practical alternatives.
Major suppliers include:
LyondellBasell
Dow
ExxonMobil
The U.S. shale gas boom has created a competitive feedstock advantage, supporting large-scale polypropylene production and export capability.
Advantages include:
Reduced shipping risk
Reliable logistics
Strong production capacity
Regulatory transparency
Lower exposure to geopolitical disruptions
Many North American buyers are increasing local sourcing to improve supply security and reduce transportation uncertainties.
Asia: Chinese Producers Gain Importance
Chinese producers have emerged as some of the largest beneficiaries of changing global trade patterns.
Key suppliers include:
Sinopec
PetroChina
Wanhua Chemical
China has expanded polypropylene production significantly in recent years and now possesses the capacity to support both domestic consumption and export growth.
For Asian buyers, Chinese suppliers often provide:
Competitive pricing
Shorter transit times
Growing export availability
Broad grade portfolios
As Middle Eastern exports decline, Chinese producers are increasingly filling supply gaps across Asia and nearby import markets.
South Asia: India's Expanding PP Industry
India's polypropylene sector continues to grow rapidly and offers attractive sourcing opportunities for regional buyers.
Leading producers include:
Reliance Industries
HPCL-Mittal Energy
India's advantages include:
Growing production capacity
Strong domestic petrochemical infrastructure
Geographic proximity to South Asian markets
Improving export competitiveness
Many South Asian converters are now prioritizing Indian suppliers as part of broader supply diversification strategies.

Europe: Regional Producers Regain Strategic Importance
European buyers are increasingly turning to regional suppliers to reduce dependence on long-distance imports.
Key producers include:
INEOS
Borealis
Although European material may carry a higher cost compared to traditional imports, many buyers view local sourcing as a strategic investment in supply reliability.
Benefits include:
Faster delivery times
Reduced logistics complexity
Improved technical support
Lower transportation risk
For critical applications, supply security is increasingly outweighing purely price-driven purchasing decisions.
Understanding PP Grades Before Qualification
One of the biggest mistakes buyers can make during supply disruptions is assuming all polypropylene grades are interchangeable.
Different applications require different material characteristics, making proper qualification essential.
Homopolymer Polypropylene
Homopolymer PP is the most widely used polypropylene grade and offers:
High stiffness
Good chemical resistance
Excellent processability
Common applications include:
Rigid packaging
Woven sacks
Housewares
Industrial containers
When switching suppliers, buyers should verify melt flow rate (MFR), mechanical properties, and processing performance.
Random Copolymer Polypropylene
Random copolymer grades contain ethylene incorporated into the polymer structure.
Benefits include:
Improved clarity
Better transparency
Enhanced flexibility
Improved impact resistance
Typical applications include:
Food packaging
Medical packaging
Consumer containers
Transparent products
Qualification should include testing optical properties, sealing performance, and process consistency.
Impact Copolymer Polypropylene
Impact copolymer grades are designed for applications requiring higher toughness.
Key advantages include:
Superior impact strength
Better low-temperature performance
Enhanced durability
Common uses include:
Automotive components
Industrial products
Appliances
Durable consumer goods
Switching suppliers requires careful evaluation of impact performance, dimensional stability, and molding characteristics.
Qualification Checklist for New PP Suppliers
Before approving an alternative polypropylene supplier, procurement teams should evaluate:
Technical Factors
Melt Flow Index (MFI/MFR)
Density
Tensile strength
Impact resistance
Food-contact compliance
Regulatory certifications
Supply Chain Factors
Production capacity
Export history
Delivery reliability
Inventory availability
Shipping routes
Risk exposure
Commercial Factors
Pricing structure
Payment terms
Contract flexibility
Volume commitments
Technical support availability
A structured qualification process reduces the risk of production disruptions and quality issues.
Market Outlook
The polypropylene market is entering a new phase characterized by regionalization and supplier diversification.
Several trends are expected to shape sourcing decisions through the remainder of 2026 and beyond:
Reduced reliance on single-source supply regions
Growth of Chinese polypropylene exports
Increased use of North American shale-based production
Expansion of Indian polymer manufacturing
Greater emphasis on supply chain resilience
More rigorous supplier qualification procedures
Even if Middle Eastern exports eventually recover, many buyers are expected to maintain diversified sourcing strategies to reduce future geopolitical risk.
Conclusion
The global polypropylene market has changed dramatically in 2026. Supply disruptions affecting traditional Middle Eastern exporters have forced buyers to rethink procurement strategies and identify new supply partners.
For North American buyers, U.S. producers offer strong alternatives. Asian buyers are increasingly turning to Chinese suppliers, while Indian manufacturers are becoming important partners for South Asian markets. European buyers are also rediscovering the value of regional sourcing through producers such as INEOS and Borealis.
Success in this environment will depend not only on finding new suppliers but also on properly qualifying polypropylene grades, managing supply chain risks, and building long-term sourcing resilience.
The companies that adapt fastest to this new reality will be best positioned to maintain stable operations in an increasingly complex global polymer market.
Ammonium Polyphosphate CAS: 68333-79-9