
Citrus Pulp CAS: 94266-47-4
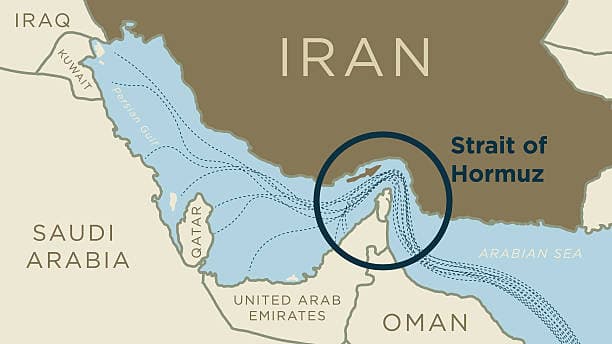
The Strait of Hormuz has seen fresh clashes that are once again cutting vessel transits, disrupting the flow of chemicals and fertilizers. These tensions elevate freight risk and threaten the stability of the global supply chain.
July 2026 presents a rare procurement opportunity for sorbitol buyers as stable Chinese feedstock costs, Thailand’s seasonal production gap, and easing freight rates combine to create one of the most attractive contracting windows of H2. Buyers with second-half demand requirements should act before supplier
The upcoming VCI Q2 2026 report underscores a sharp decline in German chemical production, driven by soaring feedstock costs and weak domestic demand. Naphtha‑based downstream plants are hit hardest, while export disruptions to Asia and the Gulf further strain utilization rates. For buyers, the data offers critical insight into supplier stability and pricing dynamics across Europe.
The sucralose market is entering a new phase in H2 2026 as changing consumer behavior linked to GLP-1 weight management therapies supports demand for low-calorie sweetness solutions. Food and beverage manufacturers are reassessing sourcing strategies as Chinese supply conditions, freight costs and contract negotiations shape delivered pricing.
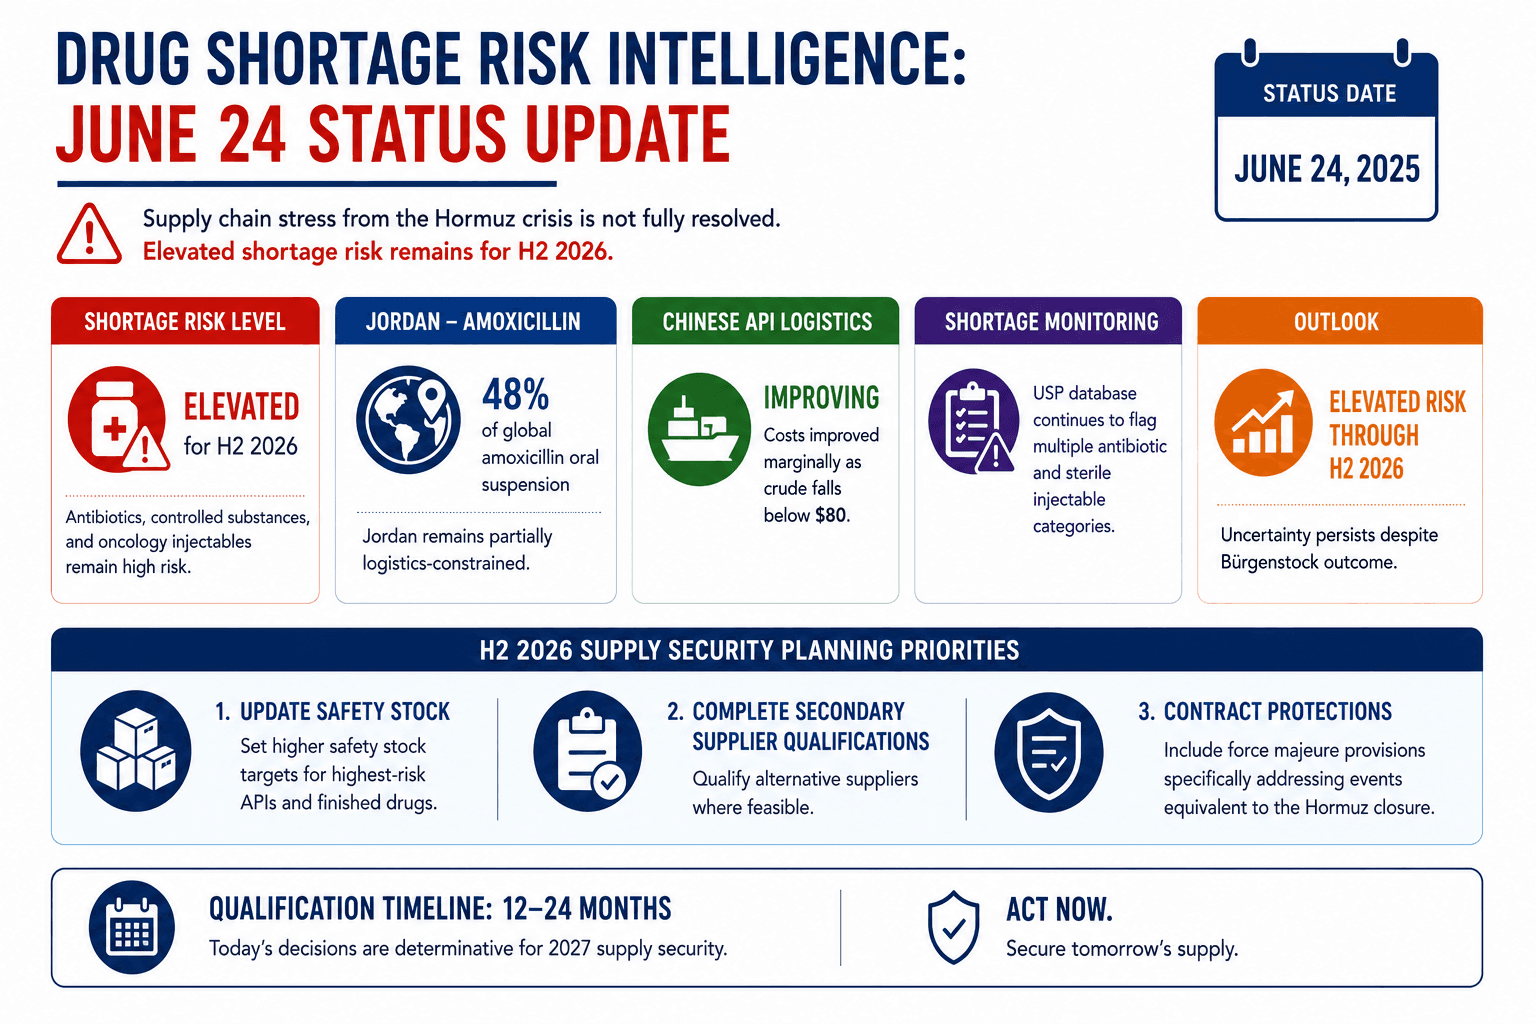
Drug shortage risk remains elevated in H2 2026 despite easing Hormuz tensions. Pharmaceutical procurement teams should prioritize safety stock updates, secondary supplier qualification, and stronger force majeure protections to secure supply continuity into 2027.
India's integrated sorbitol production capacity is strengthening its position as a reliable alternative sourcing destination.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.